Blog de artículos de BMI Brokers.

Do You Need Insurance for an eBike

Do You Need Insurance for an eBike? A Complete Guide for Safe Riding

Electric bikes—commonly known as eBikes—have become one of the most popular ways to commute, exercise, and explore cities across Europe. Affordable, sustainable, and easy to use, they offer an attractive alternative to cars and public transport. But as eBike usage grows, so does the question many riders ask: Do you need insurance for an eBike?

In this article, we break down when eBike insurance is legally required, why some riders choose to get it even when it’s optional, what typical eBike policies cover, and what safety measures every eBike owner should consider.

Do You Need Insurance for an eBike?
Do You Need Insurance for an eBike

The need for eBike insurance depends on:

  • Local laws

  • The type and power of the eBike

  • How and where you use it

In many European countries, including Spain, most standard eBikes do not require insurance. However, some high-powered models may be classified differently, and therefore require insurance similar to mopeds.

So, while you may not legally need insurance for most eBikes, it’s important to understand the classification of your specific model.

Is eBike Insurance Mandatory in Spain?

Spain classifies eBikes into two main categories:

1. Standard eBikes (Pedelecs)

  • Motor assists only when pedalling

  • Maximum assisted speed: 25 km/h

  • Motor power: 250W

  • Treated as a normal bicycle

➡️ Insurance is NOT mandatory.

2. Speed eBikes / Speed Pedelecs

  • Assistance beyond 25 km/h

  • Often more powerful motors

  • May require type approval

➡️ Insurance MAY be mandatory, depending on how the bike is classified legally.

If your electric bike is modified, faster, or more powerful than a standard pedelec, regulations may change. Always check local rules or speak with a specialist.

Why Some Riders Choose eBike Insurance Voluntarily

Even when not required, many riders decide to insure their eBikes due to:

✔️ High purchase cost

Most eBikes cost between €1,500–€5,000+. Replacing one can be expensive.

✔️ Increasing theft rates

eBikes are one of the most frequently stolen types of bicycles due to high resale value.

✔️ Liability risks

If you collide with a pedestrian or damage property, you may be held financially responsible.

✔️ Limited coverage from home insurance

Many home insurance policies don’t cover eBikes, or provide minimal protection.

Insurance can provide peace of mind for riders who want financial protection against these risks, even when not required by law.

What eBike Insurance Typically Covers

Although policies vary by provider, most eBike insurance includes:

1. Theft

Compensation if your bike is stolen from home, work, or a public space.

2. Accidental Damage

Covers crashes, falls, and collisions.

3. Vandalism

Protection from intentional damage.

4. Battery & Motor Damage

Two of the most expensive components to repair or replace.

5. Third-Party Liability

Coverage if you accidentally injure someone or damage property.

6. Personal Accident Cover (optional)

For medical expenses or rider injuries.

7. Travel Coverage (optional)

Protection if you take your eBike abroad.

Common Risks for eBike Riders

Despite their convenience, eBikes do come with risks:

  • Road traffic collisions

  • Falls caused by higher speeds

  • Battery overheating or malfunction

  • Theft in busy urban areas

  • Damage from incorrect charging

  • Weather-related deterioration

  • Crashes involving pedestrians

Being aware of these risks is the first step to riding safely.

How Much eBike Insurance Costs

The price depends on:

  • Bike value

  • Location

  • Coverage type

  • Security measures

  • Optional extras

Premiums are usually modest compared to the cost of replacing an eBike or covering damage out of pocket.

Tips for Protecting Your eBike

Whether or not you buy insurance, these steps help keep your eBike safe:

  • Use a certified high-security lock

  • Store the bike indoors whenever possible

  • Avoid leaving it unattended in public for long periods

  • Register your bike’s serial number

  • Keep proof of purchase and photos

  • Consider adding a GPS tracker

  • Follow proper battery storage and charging guidelines

A combination of good habits and security equipment significantly reduces risk.

Do You Need Insurance for an eBike: Key Takeaways

  • Most eBikes in Spain do not require insurance, but high-powered models may.

  • Many riders choose insurance voluntarily due to theft, accidents, and liability risks.

  • Standard home insurance doesn’t usually provide sufficient protection.

  • Safe habits and proper equipment greatly reduce risks.

For more helpful resources and expert guidance, visit our blog and discover detailed articles on insurance, safety, and protection in Spain.
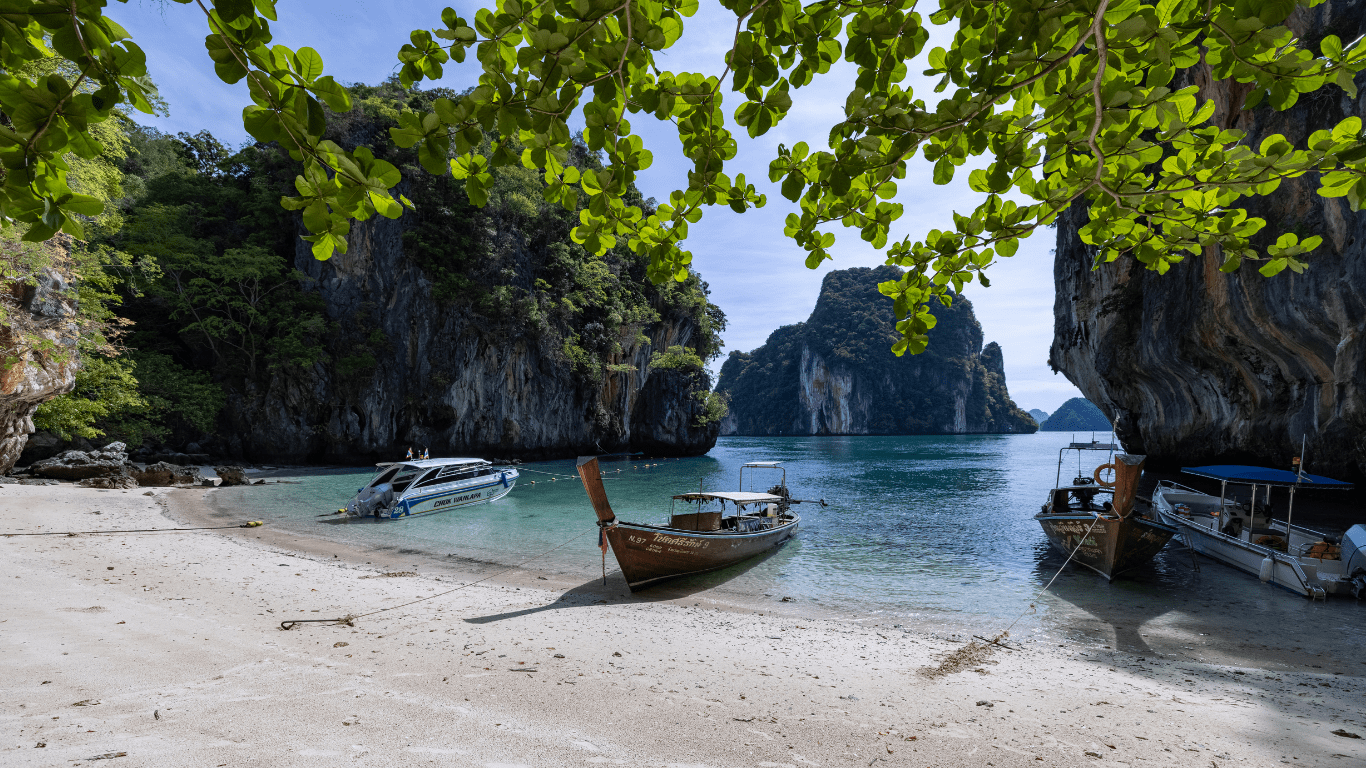
Insurance for Travelling to Thailand

Insurance for Travelling to Thailand: Everything You Need for a Safe Trip

Thailand is one of the world’s most popular travel destinations, known for its stunning beaches, vibrant culture, delicious food, and affordable luxury. Whether you’re planning a relaxing holiday in Phuket, exploring temples in Chiang Mai, or discovering the energy of Bangkok, one essential item should be at the top of your travel checklist: insurance for travelling to Thailand.

Travel insurance protects you from unexpected costs such as medical emergencies, lost luggage, trip cancellations, and more. In this complete guide, we explain why travel insurance for Thailand is essential, what it covers, how much it costs, and how BMI Brokers can help you choose the right policy for a worry-free trip.

Why You Need Insurance for Travelling to Thailand

Insurance for Travelling to Thailand

Although Thailand is generally safe and tourist-friendly, unexpected incidents can occur—especially when travelling long distances or engaging in adventurous activities. Having travel insurance for Thailand gives you peace of mind and financial protection against:

  • Medical emergencies, including hospital stays and treatment

  • Accidents during activities such as diving, trekking, or scooter riding

  • Lost, stolen, or delayed luggage

  • Trip cancellations or interruptions

  • Natural disasters or weather disruptions

  • 24/7 assistance, ensuring support anytime and anywhere

Thailand’s healthcare system is excellent, but private hospitals can be costly, especially for foreigners. Without insurance, a simple medical procedure can cost hundreds of euros—and serious incidents can reach thousands.

Travel insurance ensures you’re protected throughout your journey, no matter what happens.

What Travel Insurance for Thailand Covers

Coverage varies by provider, but most Thailand travel insurance policies include:

1. Medical and Emergency Expenses

Covers doctor visits, hospitalisation, surgery, prescription medication, and emergency transportation.

2. Trip Cancellation and Interruption

You’re protected if illness, family emergencies, or airline issues force you to cancel or return home early.

3. Lost or Delayed Luggage

Compensation for personal items, essentials, and valuable belongings.

4. Travel Delays

Coverage for meals, accommodation, and transport if your flight is significantly delayed.

5. Personal Liability

Protection if you accidentally injure someone or damage property.

6. Emergency Repatriation

Covers your return home if medically required.

7. Adventure Sports (Optional)

Many travellers to Thailand enjoy activities like diving, kayaking, and hiking. Optional add-ons extend coverage to these activities.

At BMI Brokers, we help travellers compare options and choose the right combination of coverage based on their itinerary.

Do You Need Travel Insurance to Enter Thailand?

insurance for travelling to thailand

Travel insurance is not mandatory for most tourists entering Thailand. However:

  • It is strongly recommended due to high private medical costs.

  • Some activities, tours, and volunteer programs require proof of insurance.

  • During special entry programs (e.g., pandemic periods), Thailand has required insurance—so policies may change in the future.

Regardless of requirements, insurance for travelling to Thailand is one of the best investments you can make before your trip.

Common Travel Risks in Thailand

Thailand is safe, but every destination comes with risks. The most common issues travellers face include:

✔️ Motorbike and scooter accidents

Road conditions and traffic can be challenging for foreigners.

✔️ Food-related illnesses

Street food is amazing—but sometimes unpredictable.

✔️ Weather disruptions

Tropical storms can cause flight delays or itinerary changes.

✔️ Pickpocketing in busy tourist areas

Especially in markets, beaches, and transport hubs.

✔️ Adventure activity injuries

Diving, rock climbing, and jungle trekking carry inherent risks.

Having travel insurance for Thailand ensures you receive immediate help if anything unexpected occurs.

How Much Does Thailand Travel Insurance Cost?

The cost depends on:

  • Length of stay

  • Traveller’s age

  • Type of coverage

  • Optional extras (sports, electronics, cancellations)

For most tourists, travel insurance for Thailand is affordable, especially compared to potential out-of-pocket medical costs. A short trip may cost as little as the price of a dinner—while providing essential protection.

To get an accurate quote, BMI Brokers compares top insurance providers and finds the plan that best matches your travel needs.

How to Choose the Best Travel Insurance for Your Thailand Trip

When selecting travel insurance for Thailand, consider:

1. Medical Coverage Limit

Choose a higher limit due to private hospital costs.

2. Adventure Sports Coverage

If you plan to snorkel, dive, or rent motorbikes, make sure these activities are covered.

3. Cancellation Protection

Ideal for long-haul trips booked far in advance.

4. 24/7 Assistance

Essential when travelling across time zones.

5. Trusted Providers

Work with reputable insurers experienced in international travel coverage.

BMI Brokers advises you on each point to help you make the safest choice.

Why Choose BMI Brokers for Your Thailand Travel Insurance

At BMI Brokers, we make finding the right insurance for travelling to Thailand simple and stress-free. Here’s why travellers trust us:

We compare top international travel insurance providers

Ensuring you get the best coverage at the best price.

Personalised travel protection

Based on your itinerary, activities, and length of stay.

English-speaking experts

Ideal for expats, digital nomads, and international travellers living in Europe.

Fast, easy quotes

Get your travel insurance in minutes.

Full support before and during your trip

If you need to file a claim, we guide you through the entire process.

Check out our travel insurance plans here.

Key Takeaways

  • Travel insurance for Thailand is essential to protect against medical emergencies, lost luggage, and unexpected disruptions.

  • Thailand’s private hospitals can be expensive for foreigners.

  • Insurance is not mandatory for entry, but strongly recommended.

  • Choose coverage that includes medical expenses, cancellation, and liability.

Get Your Thailand Travel Insurance Today

Make your trip unforgettable—in the best way possible. With BMI Brokers, you can travel to Thailand knowing you’re fully protected from the unexpected.

Get your personalised travel insurance quote today: discover our travel insurance plans here.
Travel smart. Travel safe. Travel insured with BMI Brokers.

Contact us today for a personalized quote and explore our blog for more travel tips, insurance guides, and expert advice. Don’t let flight cancellations ruin your trip — get covered and travel with confidence.

Title insurance in Spain

Title Insurance Spain: A Complete Guide for Safe Property Purchases

Buying property in Spain—whether for relocation, investment, or a holiday home—can be exciting, but it also comes with legal and financial risks. Issues with ownership rights, outstanding debts, boundary disputes, or hidden claims can jeopardize your investment. That’s why understanding title insurance in Spain is essential for anyone looking to purchase property with confidence.

In this guide, we explain what title insurance is, how it works in Spain, why buyers and investors rely on it, what it covers, how much it costs, and how BMI Brokers can help you secure the right protection for your real estate investment.

What Is Title Insurance in Spain?

Title insurance in Spain

Title insurance is a specialized policy designed to protect property buyers and lenders from financial losses related to defects in the property title. Unlike traditional insurance, which protects against future risks, title insurance covers past issues that were unknown at the time of purchase.

In Spain, the property buying process can involve multiple parties, historical records, and legal documents. Even with professional due diligence, errors or missing information may occur. Title insurance offers an additional layer of financial and legal protection.

Common title risks in Spain include:

  • Errors in land registry documents

  • Undisclosed heirs or ownership disputes

  • Outstanding debts or liens on the property

  • Incorrect property boundaries

  • Easements or third-party rights not properly registered

  • Fraud or forged documentation

With title insurance Spain, you can purchase property knowing that if a hidden issue arises later, your insurer will cover legal defense and compensation costs.

Why Is Title Insurance Important When Buying Property?

The Spanish property market is dynamic, but also complex—especially for expatriates or foreign investors unfamiliar with local regulations. Title insurance is important because it:

✔️ Protects against unexpected legal claims

Even after completing the purchase, someone may dispute ownership or claim rights over the property.

✔️ Covers financial losses

If the issue affects your ability to use, sell, or rent the property, the policy compensates you.

✔️ Offers peace of mind

You gain assurance that your investment is safe even if past errors come to light.

✔️ Strengthens lender confidence

Many international banks require title insurance for mortgages on Spanish properties.

What Does Title Insurance Cover?

Coverage varies by provider, but most title insurance in Spain includes protection against:

1. Ownership disputes

Claims by relatives, prior owners, or undisclosed heirs.

2. Registry errors or omissions

Inaccuracies in public records, incomplete property descriptions, or outdated information.

3. Liens and debts

Unpaid taxes, utilities, community fees, or mortgages attached to the property.

4. Easements or hidden third-party rights

Such as rights of passage, agricultural rights, or shared access not disclosed in contracts.

5. Fraud or forgery

Forgery of signatures, falsified contracts, or fraudulent property sales.

6. Legal defense costs

Your insurer covers lawyer fees and court costs related to title disputes.

A solid policy ensures that both legal representation and financial compensation are included.

Who Needs Title Insurance in Spain?

Title insurance is recommended for:

  • Foreign buyers unfamiliar with Spanish property law

  • Expat families relocating to Spain

  • Real estate investors purchasing rental or commercial property

  • Buyers of rural or older properties, where records may be incomplete

  • Developers acquiring land for construction

  • Individuals using mortgage financing

Even with a lawyer and notary review, title insurance adds a critical safety net.

Title Insurance vs. Traditional Legal Checks

Many buyers wonder whether title insurance is necessary if they already hired a lawyer. Here’s the difference:

Legal Review Title Insurance
Identifies visible risks Covers hidden or unknown risks
Based on available documentation Protects even against missing or incorrect documentation
Done before purchase Protects after purchase, often for decades
No financial compensation Full financial reimbursement for covered claims

The best protection combines both professional legal checks and title insurance.

How to Buy Title Insurance in Spain

Purchasing title insurance is straightforward. Here are the essential steps:

1. Request a Property Risk Assessment

Provide details about the property, location, and documentation.

2. Compare Insurance Providers

Not all insurers offer specialized real estate title coverage in Spain. A broker like BMI Brokers helps compare policies and identify the most reliable providers.

3. Submit Necessary Documents

This may include the nota simple, deeds, land registry information, and identification documents.

4. Review Coverage Limits and Exclusions

Ensure the policy protects against the risks relevant to your specific property.

5. Finalize and Activate the Policy

Once approved, coverage typically begins immediately upon signing.

How Much Does Title Insurance Cost in Spain?

Costs depend on factors such as:

  • Property value

  • Location

  • Type of property (urban, rural, commercial)

  • Complexity of historical records

  • Requested coverage limits

In most cases, title insurance in Spain is a small percentage of the property price, making it a highly cost-effective way to secure your investment.

For an accurate quote, professional comparison is essential.

Tips for Protecting Your Property Purchase

To minimize risks during your property transaction:

  • Always request a nota simple before making any decision.

  • Work with a reputable lawyer experienced in Spanish real estate law.

  • Ensure all debts or community fees are settled before completion.

  • Avoid paying deposits on unverified properties.

  • Consider title insurance as part of your risk-management plan.

Key Takeaways

  • Title insurance in Spain protects buyers from hidden legal and financial risks.

  • It covers ownership disputes, registry errors, debts, and fraud.

  • Ideal for expats, investors, and anyone purchasing property in Spain.

  • Combines perfectly with legal checks to maximize protection.

  • Affordable, effective, and essential for peace of mind.

Secure Title Insurance in Spain with BMI Brokers

At BMI Brokers, we help international buyers and property investors navigate the Spanish real estate system with confidence. Our team compares top title insurance providers, explains coverage options in clear terms, and guides you through the entire process from start to finish.

Protect your investment before issues arise.
Contact us today for your personalized title insurance Spain quote and ensure your property purchase is safe, secure, and stress-free.

Don’t risk driving uninsured or overpaying for coverage. Visit our blog for more tips, guides, and updates on car insurance and other essential insurance solutions.

Copayment in Health Insurance Meaning

No More Confusion: Copayment in Health Insurance Meaning Explained

At BMI Brokers, we know that understanding your health insurance plan is essential to avoid unexpected costs and make informed decisions. One term that often confuses people is copayment, also known as copay. In this guide, we explain copayment in health insurance meaning, answer common questions such as “what does copay mean in health insurance?” and “what does no copay mean in health insurance?”, and show you how we can help you get the right health insurance coverage in Spain.

What Is a Copayment in Health Insurance?

Copayment in Health Insurance Meaning

A copayment is a fixed amount that you pay out of pocket for specific medical services, such as doctor visits, prescriptions, or emergency care. This amount is separate from your monthly premium and usually applies each time you receive a service.

Understanding the meaning of copay in health insurance helps you:

  • Know your financial responsibility for medical services

  • Plan your healthcare budget effectively

  • Compare different insurance plans with confidence

For example, if your doctor visit copay is €20, you pay €20, and your insurance covers the rest. This predictable cost can help you avoid surprises while accessing the care you need.

Common Questions About Copayments

  • What Does Copay Mean in Health Insurance?

A copay is the portion of the medical bill you pay at the time of service. Copays are usually small and predictable, making routine healthcare costs easier to manage.

  • What Does Copayment Mean in Health Insurance?

Copayment is simply the full term for “copay.” It refers to the fixed payment you make for certain services, regardless of the total treatment cost. Copayments can vary depending on whether you visit a general practitioner, a specialist, or need prescriptions.

  • What Does No Copay Mean in Health Insurance?

Some health insurance plans may offer no copay for certain services. This means you won’t pay anything out of pocket for these visits or treatments—your insurance covers 100% of the cost. Plans with no copay can simplify budgeting, though premiums may be higher than plans with standard copayments.

How Copayments Work in Practice

Understanding how copayments work helps you make the most of your health insurance:

  1. Routine Doctor Visits: Most plans require a small copay, often between €15–€30.

  2. Specialist Consultations: Copays for specialists may be higher than general practitioners.

  3. Prescription Medications: Many insurance plans include a fixed copay for each prescription.

  4. Emergency Services: Copay amounts may vary depending on the hospital and service type.

We at BMI Brokers guide you through these details so you know exactly what to expect and can avoid unexpected bills.

Benefits of Understanding Copayments

Copayment in Health Insurance Meaning

Knowing about copays in your health insurance plan allows you to:

  • Budget Your Healthcare Costs: Predictable copays help you plan for medical expenses.

  • Choose the Right Plan: Compare plans based on copay amounts, coverage, and premiums.

  • Avoid Surprise Expenses: Understanding your financial responsibility prevents unwelcome surprises.

How We Help You with Health Insurance in Spain

Navigating health insurance in Spain can feel complex, especially for expatriates or non-residents. That’s where we come in. At BMI Brokers, we simplify the process:

  • Compare Top Providers: We review multiple insurance companies to find plans with the best coverage, copays, and price.

  • Offer Personalized Advice: We match your needs, lifestyle, and budget to the right health insurance plan.

  • Provide Bilingual Support: Our team speaks English and Spanish to make your experience seamless.

  • Assist with Claims: If you need to use your insurance, we guide you through the claims process efficiently and stress-free.

With our help, understanding copayment in health insurance meaning is simple, and you can choose a plan that fits your needs and your budget.
Explore our Health Insurance Plans today and contact us to get your personalized quote with BMI Brokers.

Tips for Managing Copayments

  1. Check Your Plan Details: Understand which services require copays and the amounts.

  2. Keep Records: Track your visits and copay payments for future reference.

  3. Use In-Network Providers: Insurance may cover more when you choose network providers.

  4. Ask About No Copay Options: Some plans include preventive care with no copay.

Secure Your Health Insurance with BMI Brokers Today

Don’t let copays confuse or surprise you. With BMI Brokers, you can get the right health insurance in Spain that balances coverage, affordability, and convenience.

Explore our Health Insurance Plans and discover options tailored to your needs. For personalized guidance and expert advice, contact us today to get your health insurance quote in minutes.

Protect your health, manage your costs, and enjoy peace of mind with BMI Brokers.

cheapest car insurance in spain for non residents

The Smart Guide to the Cheapest Car Insurance in Spain for Non-Residents: Expert Tips

Finding the right car insurance in Spain can be overwhelming, especially if you’re a non-resident. Driving without proper coverage is risky and could lead to serious fines or financial loss. At BMI Brokers, we specialize in helping non-residents secure the cheapest car insurance in Spain, combining affordability, comprehensive coverage, and peace of mind.

Whether you’re planning a short trip or a longer stay, this guide will help you navigate Spain’s car insurance market, compare policies, and drive safely with confidence.

Why Non-Residents Must Have Car Insurance in Spain

cheapest car insurance in spain for non residents

Spanish law requires all drivers to have valid car insurance, including non-residents. Even a minor accident without coverage can result in significant expenses, legal complications, and stress.

Proper car insurance for non-residents protects you against:

  • Accidents and vehicle damage

  • Liability for injuries to third parties

  • Theft, fire, and vandalism

  • Roadside assistance and breakdowns

At BMI Brokers, we ensure your insurance covers all essentials so you can drive worry-free.

How to Find the Cheapest Car Insurance in Spain for Non-Residents

Finding affordable insurance is more than choosing the lowest price—it’s about value, coverage, and reliability. Here’s how we help you:

1. Compare Top Insurance Providers

We review all major Spanish insurance companies to identify policies that suit your vehicle, driving experience, and stay duration.

2. Personalized Recommendations

We analyze your specific situation to recommend the most cost-effective coverage without sacrificing protection.

3. Flexible Policies

Short-term, long-term, or temporary insurance—whatever fits your travel plans, we’ve got you covered.

4. Transparent Pricing

No hidden fees, no confusing clauses. You’ll know exactly what you’re paying for.

By following these steps, non-residents can confidently secure the cheapest car insurance in Spain tailored to their needs.

Benefits of Choosing BMI Brokers for Car Insurance

cheapest car insurance in spain for non residents

At BMI Brokers, we go beyond just providing policies. Here’s why non-residents trust us:

  • Expertise in Non-Resident Policies: We understand the unique requirements of foreigners driving in Spain.

  • Competitive Rates: We find the cheapest car insurance in Spain for non-residents while ensuring full coverage.

  • Bilingual Support: Our English and Spanish-speaking team guides you every step of the way.

  • Claims Assistance: Fast, stress-free support when you need it most.

  • Comprehensive Coverage: Liability, vehicle damage, theft, roadside assistance, and more.

Tips for Non-Residents Driving in Spain

Driving in a foreign country can be challenging. Keep these tips in mind:

  • Carry your insurance documents and ID at all times.

  • Understand your policy’s limits, exclusions, and coverage areas.

  • Familiarize yourself with Spanish traffic laws and road signs.

  • Check if your international driving license is valid in Spain.

  • Keep emergency contacts and roadside assistance numbers accessible.

Frequently Asked Questions

  • Can non-residents get cheap car insurance in Spain?
    Absolutely. At BMI Brokers, we specialize in helping foreigners find affordable and reliable insurance without compromising coverage.
  • Is temporary insurance available for non-residents?
    Yes! We offer short-term and flexible policies tailored for tourists, expats, and frequent travelers.
  • Does BMI Brokers offer bilingual support?
    Yes, our team provides full support in English and Spanish for a seamless experience.

How to Get Your Car Insurance Quote Today

Getting insured with BMI Brokers is fast and simple:

  1. Visit our Car Insurance page.

  2. Enter your vehicle and personal details.

  3. Receive multiple quotes tailored to your needs.

  4. Choose the policy that fits your budget and coverage requirements.

With our expertise, finding the cheapest car insurance in Spain for non-residents is easy, fast, and stress-free.

Protect Your Car and Drive with Confidence

Driving in Spain should be enjoyable, not stressful. With BMI Brokers, you get affordable, comprehensive car insurance and expert guidance from start to finish.

Don’t risk driving uninsured or overpaying for coverage. Explore our blog for tips, guides, and updates about car insurance and other insurance solutions.

Contact us today to get your personalized quote and enjoy peace of mind on every Spanish road.

How to Insure Event Liability

How to Insure Event Liability: A Complete Guide for Safe and Successful Events

Organizing an event — whether it’s a corporate meeting, music festival, private party, or wedding — requires detailed planning and careful risk management. No matter how well you prepare, unexpected incidents can happen: a guest could be injured, property might get damaged, or a vendor could make a costly mistake.

That’s why understanding how to insure event liability is crucial. Event liability insurance protects you from financial loss and legal claims arising from accidents or injuries that occur during your event. In this guide, we’ll explain everything you need to know about how to get liability insurance for an event, what it covers, and practical steps to protect yourself and your guests.

What Is Event Liability Insurance?

How to Insure Event Liability

Event liability insurance, also known as general liability insurance for events, provides financial protection against claims resulting from injuries, property damage, or accidents that happen during an event you organize.

Whether your event is held at a private venue, a hotel, or a public space, many locations require organizers to have valid liability insurance before the event takes place. This ensures both the venue and attendees are protected if something goes wrong.

For a broader understanding of liability coverage, check our article:
How Liability Insurance Protects Your Business: A Complete Overview

Why You Need Liability Insurance for an Event

Even the best-organized events come with risks. Here are common examples where private event liability insurance can protect you:

  • Injury to guests or participants: Someone slips, trips, or falls at your event.

  • Property damage: Decorations, rented equipment, or venue property are accidentally damaged.

  • Vendor or contractor errors: A catering or technical team causes an incident resulting in a claim.

  • Alcohol-related incidents: Serving drinks can increase liability risks.

Without proper insurance, you could be personally responsible for compensation, legal costs, and damages — all of which can quickly add up.

Event liability insurance offers peace of mind, ensuring you’re financially protected so you can focus on running a successful event.

How to Get Liability Insurance for an Event

Wondering how to get liability insurance for an event? The process is simpler than most organizers think. Follow these essential steps:

1. Assess Your Event’s Risk Level

Start by evaluating the type of event, expected attendance, duration, and potential hazards. Outdoor festivals, concerts, and sporting events, for instance, carry higher risks than small indoor gatherings.

2. Determine Coverage Limits

Decide on coverage limits based on your event’s risk exposure and venue requirements. Some venues specify minimum coverage amounts to ensure adequate protection.

3. Compare Insurance Providers

Research multiple providers and compare policy features, exclusions, and costs. Look for insurers who specialize in private investigation insurance or event-related coverage, as they understand the unique risks associated with public gatherings.

4. Provide Detailed Event Information

Insurance companies typically ask for event details, including:

  • Type and location of the event

  • Number of attendees

  • Use of third-party vendors or subcontractors

  • Presence of alcohol, fireworks, or special effects

The more accurate your information, the more tailored and effective your policy will be.

5. Review Policy Terms Carefully

Before finalizing your policy, read the fine print. Ensure your coverage includes protection for bodily injury, property damage, and legal defense costs. Ask whether the policy extends to vendors or subcontractors.

Understanding General Liability Insurance for Events

How to Insure Event Liability

General liability insurance for an event typically covers:

  • Third-party bodily injury

  • Property damage

  • Legal defense and court costs

  • Tenant or venue damage liability

  • Some policies may also include host liquor liability coverage

The cost of coverage depends on several factors, including event size, duration, and location. To estimate how much event liability insurance costs, contact a licensed broker who can compare multiple insurers and find competitive rates tailored to your needs.

If you want to understand how broader liability insurance works beyond events, read our guide on Civil Liability Insurance: What You Need to Know for Complete Protection.

Tips to Minimize Risks at Your Event

Insurance is essential, but prevention remains your best defense. Here are proactive measures to reduce risks:

  • Conduct a thorough risk assessment before the event.

  • Require all vendors to provide proof of their own liability insurance.

  • Train staff and volunteers on safety and emergency procedures.

  • Keep first aid stations and safety equipment readily available.

  • Use clear signage to guide attendees and prevent accidents.

By combining preventive planning with insurance protection, you ensure your event runs smoothly and safely.

How Much Does Event Liability Insurance Cost?

Many organizers ask, “How much does event liability insurance cost?” — and the answer depends on several factors:

  • Type of event: Weddings or conferences may cost less to insure than concerts or festivals.

  • Number of attendees: Larger events mean higher potential risk.

  • Venue location: Some areas have stricter insurance requirements.

  • Coverage limits: Higher protection levels increase premiums.

While prices vary, the cost is usually modest compared to the potential financial losses from an uninsured incident. Always request multiple quotes to find the right balance between cost and coverage.

Key Takeaways

  • Event liability insurance protects organizers from financial and legal risks.

  • It’s often required by venues and local regulations.

  • Coverage typically includes bodily injury, property damage, and legal defense.

  • Costs depend on event type, size, and coverage limits.

  • Prevention and proper planning reduce risk and improve safety.

Contact Us and Stay Informed

At BMI Brokers, we’re committed to helping professionals, residents, and event organizers in Spain stay informed about insurance, risk management, and financial protection. Understanding how to insure event liability is a key step in organizing safe and successful events.

If you have questions or want to learn more about insurance options and best practices, contact us today. Our team is here to help you make confident, informed decisions.

Explore more of our blog for expert insights and practical guides on liability, business, and personal insurance — including:

Stay informed. Stay protected. Stay confident with BMI Brokers.

Private Investigator Insurance

Private Investigator Insurance: Comprehensive Guide for Professionals

Are you a private investigator looking to understand the risks and coverage options in your field? Private investigator insurance is essential for protecting your business, equipment, and reputation. Whether you operate independently or collaborate with insurance companies, knowing how insurance works in your profession is key to operating confidently.

In this guide, we’ll explore private investigator insurance, what it covers, costs, liability protection, and how insurance companies use investigators. We’ll also answer common questions every professional should know.

What Is Private Investigator Insurance?

Private Investigator Insurance

Private investigator insurance is a type of professional coverage that protects investigators against financial losses arising from accidents, lawsuits, or professional mistakes. Investigators face unique risks: property damage, personal injury claims, or errors in gathering evidence can lead to costly legal action.

Coverage typically includes:

  • General liability insurance – protection against claims from third parties for bodily injury or property damage.

  • Professional liability / errors & omissions insurance – covers mistakes, negligence, or misrepresentation in investigative work.

  • Equipment coverage – protects cameras, surveillance tools, vehicles, and other essential investigative equipment.

This insurance ensures investigators can focus on their work without risking financial ruin from unforeseen incidents.

Why Private Investigator Insurance Is Important

Investigation work often involves unpredictable situations. Some common risks include:

  • Accidental property damage during surveillance.

  • Injuries to third parties on location.

  • Professional errors leading to client disputes.

  • Liability claims when working with insurance companies.

With the right private investigation insurance, these risks can be managed effectively, giving you confidence and professional credibility in your work.

How Private Investigation Insurance Coverage Works

Understanding the scope of private investigator insurance coverage helps you choose the right policy. Standard options include:

  1. Private investigator liability insurance – protects against property damage and bodily injury claims.

  2. Professional liability insurance – also known as errors and omissions insurance, it covers mistakes in your investigative work.

  3. Equipment coverage – insures essential tools, such as cameras, vehicles, computers, and recording devices.

  4. Cyber liability – protects sensitive data, client information, and digital investigations.

Combining these policies can provide complete protection for your business operations.

How Much Does Private Investigator Insurance Cost?

A frequent question is: “how much does private investigator insurance cost?” The price varies based on:

  • The size of your business and number of employees.

  • Coverage limits and policy type.

  • The types of investigations you conduct.

  • Your location and risk exposure.

Typically, annual premiums range from a few hundred to a few thousand dollars, depending on coverage. Requesting a personalized quote ensures you have adequate protection tailored to your needs.

Do Insurance Companies Hire Private Investigators?

Yes. Insurance companies often hire private investigators for:

  • Verifying claims and detecting fraud.

  • Conducting surveillance or background checks.

  • Investigating suspicious insurance claims.

People also ask:

  • “Do insurance companies use private investigators?”

  • “How often do insurance companies use private investigators?”

The answer depends on the insurer and the type of claims. For high-value claims or potential fraud cases, private investigators play a critical role in risk management and claim verification.

Types of Private Investigator Insurance

The main types of coverage include:

  • General liability insurance – protects against injuries or damages to third parties.

  • Professional liability insurance – covers legal claims from errors or negligence in professional work.

  • Equipment coverage – protects surveillance cameras, computers, vehicles, and other tools.

  • Cyber liability insurance – covers data breaches or mishandling of sensitive client information.

Choosing the right combination of policies ensures full protection against the risks of private investigation.

Key Benefits of Private Investigator Insurance

  1. Financial protection against lawsuits and damages.

  2. Peace of mind for investigators and clients alike.

  3. Professional credibility when working with insurance companies or clients.

  4. Coverage for equipment, which is often expensive to replace.

  5. Protection against errors and omissions, preventing costly legal disputes.

Frequently Asked Questions (FAQs)

  • What is private investigation insurance?
    It’s a policy that protects private investigators from liability, professional mistakes, and damage to property or equipment.
  • Do insurance companies hire private investigators?
    Yes, especially for fraud detection, claims verification, and high-value cases.
  • How much does private investigator insurance cost?
    Costs vary by coverage, location, and business size, generally ranging from a few hundred to several thousand dollars annually.
  • What does private investigator liability insurance cover?
    It covers third-party bodily injury, property damage, and legal expenses resulting from investigative work.
  • Do I need equipment insurance?
    Yes, cameras, vehicles, and electronic devices are essential tools that can be costly to replace if damaged or stolen.

Conclusion: Protect Your Business with BMI Brokers

At BMI Brokers, we provide expert resources and insights to help professionals stay informed about insurance, risk management, and professional protection. Understanding private investigator insurance is crucial for safeguarding your business, equipment, and reputation.

Contact Us and Stay Informed

If you have questions or want to learn more about insurance options, contact us today. Our team is ready to help you make informed, confident decisions tailored to your professional needs.

Continue exploring our blog for additional tips, guides, and expert advice on insurance and risk management in Spain, and stay ahead in protecting your business and assets.

What Are Construction Site Insurance Requirements

What Are Construction Site Insurance Requirements? A Builder’s Guide to Risk and Compliance

If you’re managing or working on a construction project in Spain or anywhere in Europe, understanding the insurance requirements for construction sites is essential. Construction work involves significant financial, legal, and safety risks — from property damage to worker injuries — and having the right insurance in place is both a legal necessity and a smart business decision.

In this guide, we’ll explain what are construction site insurance requirements, the different types of coverage involved, who needs them, and why they’re so important for contractors, builders, and property owners.

What Is Construction Site Insurance?

What Are Construction Site Insurance Requirements

Construction site insurance is a collection of policies designed to protect construction companies, contractors, and property owners from financial loss due to accidents, injuries, or property damage occurring during a building project.

Each project faces unique risks, so insurance requirements vary depending on project size, scope, and location. However, in most cases, certain types of coverage are mandatory by law or contract.

Why Is Construction Insurance Required?

Construction sites can be unpredictable environments. Heavy machinery, structural work, and multiple contractors increase the risk of accidents and damage.

Insurance is required to:

  • Protect employees and third parties from injury-related claims.

  • Cover damage to property, materials, or equipment.

  • Comply with legal and contractual obligations.

  • Safeguard against project delays and financial loss.

Without proper insurance, even a minor incident could lead to major financial or legal consequences.

Key Construction Site Insurance Requirements

Here are the main types of insurance that construction projects typically require:

1. Public Liability Insurance

This policy protects against claims from third parties (such as the public, visitors, or nearby property owners) for injury or property damage caused by construction activities.

Example: If construction debris damages a neighbouring building or a passer-by is injured near the site, public liability insurance covers the compensation and legal costs.

Requirement: In most jurisdictions, including Spain and the UK, contractors must hold valid public liability insurance before starting any work on-site.

2. Employer’s Liability Insurance

If you employ staff or subcontractors, employer’s liability insurance is legally required in many countries.

It covers compensation costs if an employee is injured or becomes ill due to work-related activities.

Example: A worker suffers a fall or a back injury while handling materials — this policy ensures they receive medical and wage compensation.

3. Contractors All Risks (CAR) Insurance

CAR insurance provides comprehensive protection for both the construction works and materials on-site.

It covers accidental damage to the structure being built, theft of materials, or damage from unforeseen events such as fire or storm.

This policy often includes both the contractor and the project owner as named insured parties, ensuring both are protected financially.

4. Professional Indemnity Insurance

Professional indemnity insurance (PI) protects architects, engineers, and consultants involved in the design and planning stages of construction projects.

It covers claims resulting from professional errors, negligence, or omissions that cause financial loss or project delays.

For example, if an engineering miscalculation leads to structural issues, PI insurance would help cover the resulting claims.

5. Workers’ Compensation and Personal Accident Cover

In addition to employer’s liability insurance, workers’ compensation ensures that all workers are covered for injuries sustained on the job, including medical treatment, lost wages, and rehabilitation costs.

Some contractors also choose to include personal accident cover for self-employed workers who might not be covered under standard employment policies.

Who Needs Construction Site Insurance?

What Are Construction Site Insurance Requirements

Construction site insurance requirements apply to a wide range of professionals and organisations, including:

  • General contractors and subcontractors

  • Developers and property owners

  • Architects and engineers

  • Equipment suppliers

  • Project managers and site supervisors

Even if you’re working as a subcontractor or freelancer, many clients and principal contractors will require proof of valid insurance before allowing you to work on-site.

Legal and Regulatory Considerations

Insurance requirements may differ depending on your country or local regulations. In Spain, for example:

  • Construction companies are generally required to have liability coverage in place.

  • Large-scale projects or public contracts often require additional performance bonds or guarantees.

  • Developers must provide 10-year structural warranties (decennial insurance) for new builds to protect homeowners from future structural defects.

Always verify requirements with your local authority or project manager before work begins.

Tips for Managing Risk on Construction Projects

Even with full insurance coverage, prevention is always the best strategy. Here are a few key tips for managing on-site risks:

  • Conduct regular safety training and enforce site rules.

  • Maintain detailed risk assessments for each project phase.

  • Keep equipment and machinery in good working condition.

  • Ensure all subcontractors have valid insurance certificates.

  • Review and update your insurance policies annually or before each new project.

Key Takeaways

  • Construction site insurance is essential for protecting workers, property, and third parties.

  • Common requirements include public liability, employer’s liability, CAR, and professional indemnity insurance.

  • Many policies are legally mandatory and required by contract.

  • Compliance helps avoid costly claims, delays, and penalties.

  • Always check local laws and project-specific conditions.

Conclusion: Stay Informed and Keep Learning with BMI Brokers

Understanding what are construction site insurance requirements is crucial for anyone involved in building projects, from contractors to property owners. Staying informed ensures compliance, safety, and financial protection for everyone on-site.

If you found this article helpful, we invite you to keep exploring our blog for more expert insights on insurance, property protection, and financial security in Spain.

Stay informed — and stay protected — with the latest guides from BMI Brokers.

What is flood insurance

What Is Flood Insurance? Complete Guide to Protecting Your Home in Spain

If you’ve ever asked yourself what is flood insurance, and do I really need it in Spain?” — you’re not alone. Floods and heavy rain are becoming more common across the country, and many homeowners are surprised to discover that standard home insurance policies may not cover all types of flood damage.

At BMI Brokers, we know how devastating water damage can be. That’s why it’s so important to understand how flood insurance works, what it covers, and how you can protect your home — and your finances — from costly repairs.

In this guide, we’ll explain everything you need to know about flood insurance in Spain, including the difference between home and flood insurance, what’s covered, how much it costs, and how to get full protection through our comprehensive home insurance options.

What Is Flood Insurance?

What is flood insurance

Flood insurance is a type of coverage that protects homeowners against loss or damage caused by flooding, heavy rain, overflowing rivers, or natural disasters involving water. While standard home insurance may cover certain types of water damage (like leaks or burst pipes), it typically excludes flooding from external sources.

Having flood insurance ensures that you’re financially protected if rising water or storms damage your property or belongings.

What Does Flood Insurance Cover?

A dedicated flood insurance policy or flood add-on to your home insurance typically covers:

  • Structural damage to your home’s walls, floors, and foundations.

  • Damage to fixtures and fittings, including kitchens, bathrooms, and built-in wardrobes.

  • Replacement of personal belongings such as furniture, electronics, and clothing.

  • Cleanup and restoration costs after the floodwater recedes.

  • Temporary accommodation expenses while your property is being repaired.

However, most policies don’t cover preventable damage — for example, neglecting maintenance or ignoring known drainage problems. Always check your policy terms for exclusions.

Flood Insurance vs. Home Insurance: Key Differences

Home insurance and flood insurance are closely related, but they serve different purposes.

  • Home insurance (buildings and contents) covers incidents like fire, theft, leaks, or burst pipes.

  • Flood insurance covers damage caused by water entering your property from outside due to storms, overflowing rivers, or extreme rainfall.

At BMI Brokers, our home insurance plans can include optional flood cover to ensure you’re fully protected — without the need to purchase two separate policies. This integrated approach gives you convenience, cost efficiency, and peace of mind.

How Flood Insurance Works in Spain

In Spain, flood coverage can be a little more complex than in other countries. Major natural disasters, including catastrophic floods, are often managed by the Consorcio de Compensación de Seguros (CCS) — a government-backed fund that compensates policyholders for extraordinary risks.

To be eligible for CCS compensation, your home insurance policy must already include natural disaster coverage. That’s why choosing the right provider matters: at BMI Brokers, we make sure your policy includes all the required protections so you’re not left uncovered when you need it most.

Do You Really Need Flood Insurance?

You might think flooding isn’t a concern unless you live near a river or the coast, but heavy rain and flash floods can happen anywhere in Spain — especially during autumn storms and gota fría weather events.

We’ve seen many cases where homeowners without flood insurance faced thousands of euros in repair costs after just one night of heavy rainfall.

If you live in flood-prone areas such as Málaga, Alicante, Valencia, or along the Costa del Sol, having flood insurance is not just advisable — it’s essential. Even inland areas have experienced unexpected flooding in recent years.

How Much Does Flood Insurance Cost?

The cost of flood insurance depends on several factors:

  • Your location and flood risk level (proximity to rivers or coastal areas).

  • The type and age of your property.

  • Your coverage limits and deductible (excess) amount.

  • Whether flood cover is included within your existing home insurance.

In general, adding flood coverage to your BMI Brokers home insurance plan is surprisingly affordable — often just a small percentage increase in your annual premium for a significant boost in protection.

Our team can provide a personalised quote and compare multiple insurers to find the best coverage at the best rate.

How to Get Flood Coverage with BMI Brokers

At BMI Brokers, we specialise in helping expats and residents in Spain find comprehensive and reliable insurance solutions. When you take out home insurance with us, we can include flood protection that covers both structural and content damage caused by severe weather or rising water.

Our process is simple:

  1. We assess your property and its flood risk level.

  2. We compare leading insurers in Spain to find policies with full flood cover.

  3. We tailor your plan to your home and budget.

  4. We handle the paperwork and ensure your coverage is active and compliant.

Learn more about our Home Insurance in Spain and how it can protect you from unexpected flooding and water damage.

Key Takeaways

  • Flood insurance covers damage caused by external water sources, not just internal leaks.

  • It’s not always included in standard home insurance — you may need to add it.

  • In Spain, the Consorcio de Compensación de Seguros may step in for major disasters.

  • At BMI Brokers, we can include flood coverage directly in your home insurance policy.

  • Protecting your property now can save thousands in future repair costs.

Conclusion: Protect Your Home with BMI Brokers

Flooding can strike when you least expect it, leaving behind costly repairs and emotional stress. Having the right coverage in place gives you peace of mind that your home and possessions are protected.

At BMI Brokers, we’re here to help you understand every aspect of your policy and make sure you have comprehensive home and flood insurance that fits your needs.

Contact us today for a free, personalised quote and let our experts protect what matters most — your home, your peace of mind, and your future.

Ready to stay ahead and make empowered decisions? Visit our blog today and discover a wealth of resources tailored just for you.

What is a Car Insurance Excess

What is a Car Insurance Excess? Complete Guide to Understanding Your Policy

If you’ve ever wondered what is a car insurance excess, you’re not alone. Understanding how excess works is essential for any car owner or driver looking to protect their vehicle and finances. A car insurance excess is the amount you agree to pay out of pocket when making a claim, and it can significantly affect your insurance premium and overall costs.

In this guide, we’ll explain the different types of car insurance excess, including voluntary and hire car excess, and show you how to choose the right excess for your needs. By the end, you’ll have a clear understanding of how to manage your car insurance effectively and make informed decisions to safeguard your money.

What is a Car Insurance Excess?

What is a Car Insurance Excess

A car insurance excess is the amount you agree to pay out of pocket if you make a claim on your car insurance policy. It’s designed to share the risk between you and your insurer, helping keep premiums more affordable.

For example, if your policy has a £500 excess and you make a claim of £2,000, you will pay £500 and your insurer covers the remaining £1,500. Understanding how excess works is crucial to managing costs and choosing the right coverage for your vehicle.

What is Excess in Insurance?

Excess in insurance is the general term for the amount a policyholder contributes towards a claim. It applies not only to car insurance but also to home, travel, and other types of insurance.

Insurance excess can be:

  • Compulsory excess: Set by the insurer, often based on your driving record or vehicle type.

  • Voluntary excess: Chosen by you, usually to lower your premiums.

By understanding what excess is in insurance, you can make informed decisions about the coverage that suits your budget and risk tolerance.

Voluntary Excess on Car Insurance

Voluntary excess is an additional amount you agree to pay on top of your compulsory excess. Choosing a higher voluntary excess can reduce your insurance premium, but it also increases your out-of-pocket costs if you make a claim.

Key points about voluntary excess:

  • Helps lower your monthly or annual premium.

  • Should match your ability to pay in case of an accident.

  • Can be adjusted when renewing your policy to reflect changes in your financial situation.

Car Hire Excess Insurance Explained

What is a Car Insurance Excess

If you hire a car, most rental companies include an excess in the insurance they provide. This is the car hire excess, the maximum amount you would pay if the vehicle is damaged.

Car hire excess insurance is a separate policy that covers this excess, often at a lower cost than paying the full amount directly to the rental company. Benefits include:

  • Full protection against damage or theft claims.

  • Peace of mind while driving abroad or in unfamiliar areas.

  • Cost savings in case of minor accidents or incidents.

Understanding the Excess Amount in Car Insurance

The excess amount in car insurance depends on several factors:

  • Vehicle type: Expensive or high-performance cars usually have higher excess.

  • Driver profile: Age, experience, and claims history can affect the excess.

  • Policy type: Comprehensive policies may have different excess amounts than third-party coverage.

It’s important to read your policy documents carefully and ensure you understand the exact excess amounts that apply.

How to Choose the Right Excess for Your Policy

When selecting your car insurance excess:

  1. Evaluate your budget: Make sure you can afford the excess if you need to claim.

  2. Compare premiums: Higher voluntary excess can reduce your premium, but balance savings against potential costs.

  3. Consider car hire plans: If you rent cars often, car hire excess insurance can be worthwhile.

  4. Check for discounts: Some insurers offer lower excess for safe drivers or multi-policy holders.

Choosing the right combination of compulsory and voluntary excess ensures your policy is affordable and your finances are protected.

Conclusion: Protect Your Finances with the Right Car Insurance Excess

Understanding what a car insurance excess is and how it works can save you money and avoid surprises in the event of a claim. By choosing the right excess amount and considering options like voluntary or car hire excess insurance, you can travel, drive, and rent vehicles with confidence.

Explore our car insurance options and get expert advice to find the best policy for your needs.

Contact us today for a personalized quote and full protection on your car insurance.