Blog de artículos de BMI Brokers.

What Documents Do I Need for ITV in Spain

What Documents Do I Need for ITV in Spain? Your 2025 Checklist

If you’re preparing for your next ITV car inspection in Spain, one of the most common questions is: What documents do I need for ITV in Spain? Whether you’re a long-term resident or a newcomer just getting started, knowing exactly what to bring to the inspection station is essential to ensure a smooth and successful process.

In this guide, we’ll break down all the necessary paperwork, provide some expert tips to avoid delays, and show you how this ties into your broader vehicle responsibilities — from registration to car insurance.

What Is the ITV in Spain?

The ITV (Inspección Técnica de Vehículos) is Spain’s mandatory vehicle inspection system designed to ensure road safety and environmental compliance. Depending on your vehicle type and age, you will need to go through the ITV regularly, and being unprepared can result in failed inspections or fines.

If you’re still unfamiliar with the basics, check out our article: What is ITV in Spain? A Quick Guide It covers what ITV is, how it works, and who needs it.

So, What Documents Do I Need for ITV in Spain?

What Documents Do I Need for ITV in Spain

Make sure you have the necessary documents for ITV in Spain, including your vehicle registration and ID.

Before heading to your ITV appointment, make sure you have these documents ready:

  1. Permiso de Circulación (Vehicle Registration Certificate)
    This is your official vehicle registration in Spain.

  2. Ficha Técnica (ITV Card)
    This document is your vehicle’s technical inspection sheet. It contains essential data about the vehicle and past inspection results. If you’re wondering what exactly the ITV card Spain looks like or what happens if it’s missing — stay tuned, we’ll cover that below.

  3. DNI/NIE or Passport
    A form of identification proving you are the vehicle owner or authorized driver.

  4. Valid Insurance Proof
    While not always requested, it’s advisable to carry proof of current car insurance coverage. If you’re looking for reliable coverage, explore our car insurance services at BMI Brokers.

What If You’ve Lost Your ITV Card in Spain?

If you’ve lost your ITV card in Spain, don’t panic — you can request a duplicate. Here’s what to do:

  • Visit your local ITV Spain website or inspection center.

  • Request a duplicate of the ficha técnica.

  • Bring your vehicle documentation and identification.

  • A small fee may apply, and some centers may ask for a police report if the document was stolen.

Keeping the ITV card Spain up-to-date is crucial, as the inspection center won’t proceed without it.

How Does This Fit into Your Car ITV in Spain Routine?

Bringing the right documents is just one part of ensuring your car ITV in Spain is a success. You’ll also want to check that:

  • Your lights, brakes, and tires are in good condition.

  • Emissions meet current standards.

  • Your insurance is up to date.

Want to know more about recent inspection changes? Then don’t miss: New ITV Rules in Spain: Essential Changes You Need to Know This guide outlines the latest updates in emissions tests, fines, and what’s being checked during inspections.

Booking Your ITV Appointment Online

Once your documents are ready, you can book your inspection online. Each autonomous community in Spain has its own system, so it’s best to visit your regional ITV Spain website.

Need help with this process? We’ve got you covered: How to Book an ITV Appointment in Spain: A Step-by-Step Guide This article shows you exactly how to schedule your appointment and what to expect on the day.

Final Checklist: Don’t Leave Home Without These

To summarize, here’s your go-to list for what documents do I need for ITV in Spain:

Document Purpose
Vehicle Registration Certificate Confirms legal ownership
ITV Card (Ficha Técnica) Technical history of the vehicle
ID (DNI/NIE or Passport) Verifies your identity
Insurance Document Proof of current coverage

Make sure all your papers are originals or valid copies, and that none are expired.

Stay Compliant and Protected with BMI Brokers

At BMI Brokers, we help you go beyond the car ITV in Spain — by ensuring you have complete car insurance coverage that meets local requirements. From paperwork to protection, we’ve got your back.

Whether you’re new to the ITV Spain website, need help getting a duplicate ITV card Spain, or simply want peace of mind before your next inspection, we’re here to help.

For more details, feel free to visit our blog and explore more expert insights. Trust BMI Brokers to guide you through the complexities of insurance policies tailored to your specific needs. Contact us today!

civil liability insurance

Civil Liability Insurance: What You Need to Know for Complete Protection

When it comes to protecting your business or personal assets, civil liability insurance is one of the most crucial types of coverage to consider. This comprehensive guide will explain everything you need to know about civil liability insurance, its benefits, and how it works to safeguard you from potential legal claims.

What is Civil Liability Insurance?

Civil liability insurance provides financial protection for individuals and businesses against claims that arise due to negligence, errors, or omissions that cause damage to other parties or their property. Whether you own a small business or are a professional offering services, this insurance ensures that you’re covered when a lawsuit or legal claim occurs.

Unlike other types of coverage, civil liability insurance addresses claims that fall outside the scope of traditional property or health insurance. It typically covers legal fees, settlements, and any damages awarded to the other party involved.

Civil Liability Insurance in Spain

For businesses operating in Spain, it’s essential to understand the nuances of civil liability insurance in Spain. The legal landscape and requirements may differ, and understanding local regulations can help businesses avoid costly mistakes. Spain has specific laws and standards that require certain businesses to have liability coverage. Understanding these regional differences ensures your business remains compliant and protected.

Types of Civil Liability Insurance

civil liability insurance

Civil liability insurance helps protect you from potential legal claims and risks.

There are several types of civil liability insurance that provide coverage for different risks. Some of the most common include:

  • General Liability Insurance: This protects businesses from a wide range of claims, including those for bodily injury, property damage, or personal injury that occur as a result of business operations.

  • Professional Liability Insurance: Also known as professional indemnity insurance, it protects professionals from claims related to negligence or errors in the services they provide. This is especially critical for consultants, doctors, lawyers, and other service-oriented professions.

  • Public Liability Insurance: This coverage protects against claims from members of the public who may be injured or whose property may be damaged due to your business activities.

Benefits of Civil Liability Insurance

Opting for civil liability insurance can offer numerous advantages for both individuals and businesses:

  1. Financial Protection: This type of insurance covers legal costs, settlements, and damages, providing essential financial support when facing a lawsuit.

  2. Peace of Mind: With the right coverage, businesses and professionals can focus on growth and operations, knowing they are protected from unforeseen legal claims.

  3. Reputation Management: A legal dispute can harm your business’s reputation. Civil liability insurance helps manage these situations effectively, preventing significant damage to your image.

  4. Legal Compliance: Many industries require civil liability insurance to meet legal and regulatory standards. Having the right policy ensures that your operations are compliant with local laws.

How to Choose the Right Civil Liability Insurance

Choosing the right civil liability insurance involves several steps:

  1. Assess Your Risks: Analyze the nature of your business or professional services to determine the coverage limits and types of claims you may face.

  2. Compare Policies: Ensure that the policies you are reviewing provide adequate coverage and at a competitive price. It’s also crucial to compare exclusions and additional benefits.

  3. Consult with Experts: Speak to an insurance broker or expert who can help tailor a policy that fits your specific needs.

  4. Review the Fine Print: Always review the policy’s terms, exclusions, and coverage limits to avoid unexpected gaps in coverage.

Civil Liability Insurance and Risk Management

Civil liability insurance is an essential part of a broader risk management strategy. By identifying potential liabilities, businesses can implement measures to prevent claims from occurring. Regular risk assessments and clear contracts can help minimize the chances of facing a claim, and civil liability insurance will provide the safety net you need when the unexpected happens.

Learn More About Liability Insurance

If you want to dive deeper into the world of liability coverage, check out our article on How Liability Insurance Protects Your Business for a more detailed exploration of general liability insurance, professional liability, and other related policies.

Frequently Asked Questions (FAQs)

  • What is the difference between civil liability and general liability insurance?

While both cover legal claims, civil liability is a broader term that includes various types of liability, such as personal and professional liability. In contrast, general liability insurance is specifically aimed at covering claims of bodily injury or property damage resulting from business operations.

  • Do I need civil liability insurance if I work from home?

Yes, even if you’re working from home, civil liability insurance is still important. It protects you from claims that may arise due to accidents or damages that occur as part of your business activities, even in a home setting.

  • How much does civil liability insurance cost?

The cost of civil liability insurance varies depending on factors like business size, industry, and risk profile. To get an accurate quote, it’s recommended to consult with an insurance broker who can assess your needs and provide the best coverage options.

Civil Liability Insurance: Conclusion

Civil liability insurance is a must-have for anyone looking to protect their business or personal assets against unexpected legal claims. By understanding the types of coverage available and selecting the right policy, you can ensure peace of mind and secure your financial future. Don’t wait for an incident to happen—ensure you’re properly covered today.

For more details on insurance coverage, feel free to visit our blog and explore more expert insights. Trust BMI Brokers to guide you through the complexities of insurance policies tailored to your specific needs. Contact us today!
third party insurance coverage

Third Party Insurance Coverage: What It Is and Why You Need It

When it comes to car insurance, one of the most common terms you’ll encounter is third party insurance. But what is third party insurance mean, and how does it work? In this article, we’ll explore the definition, coverage, and benefits of third party car insurance, helping you make an informed decision about your insurance needs.

What is Third Party Insurance Coverage?

Third party insurance is a type of insurance policy that protects you against claims made by other parties if you cause damage or injury to them in an accident. It does not cover your own vehicle or injuries, making it one of the most basic and affordable car insurance options.

In simple terms, third party insurance is a coverage that ensures the financial protection of others, not yourself. If you’re involved in a collision and are at fault, this insurance will cover the damages to the other driver’s vehicle, as well as their medical expenses or property damage, depending on the specifics of the policy.

What Does Third Party Insurance Cover?

third party insurance coverage

Many countries require drivers to have third party insurance coverage to ensure compensation for accident victims.

A standard third party car insurance policy typically covers the following:

  • Bodily Injury Liability: Covers medical costs and legal expenses for injuries caused to other people in an accident where you are at fault.

  • Property Damage Liability: Pays for the damage caused to other people’s property, including their car, buildings, fences, and other property.

  • Legal Fees: Covers any legal costs that may arise if a lawsuit is filed against you due to the accident.

However, third party insurance does not cover your own vehicle or injuries. For this, additional coverage options, such as comprehensive insurance, are available.

How Does Third Party Insurance Work?

The basic premise of third party insurance is that it protects others from the consequences of your actions in the event of an accident. Here’s a step-by-step breakdown of how it works:

  1. Accident Occurs: You are involved in a car accident and are found to be at fault.

  2. Claim Filed: The other party (the third party) files a claim with your insurer for the damage to their vehicle or any injuries.

  3. Insurer Pays: Your insurance company covers the costs for the damage or injuries up to the policy limits. However, your own vehicle or personal injuries are not covered.

This is why third party insurance is often considered the minimum level of car insurance required by law in many countries.

What is Extended Third Party Insurance?

If you’re looking for more coverage than basic third party insurance, you might want to consider extended third party insurance. This typically includes additional protections, such as coverage for fire and theft, which are not part of standard third party policies.

While extended third party insurance is still cheaper than comprehensive insurance, it provides more peace of mind by covering incidents like theft or damage to your car from a fire.

Is Third Party Insurance Enough for You?

While third party insurance is the most basic option, it’s often enough for those who drive older vehicles or those who are looking for the cheapest option to meet legal requirements. However, if you want protection for your own car and injuries, you’ll need to consider comprehensive insurance.

Comprehensive insurance not only covers damages to third parties but also protects your own vehicle, regardless of fault, offering a broader scope of coverage.

What Are the Differences Between Third Party and Comprehensive Insurance?

Understanding the differences between third party insurance and comprehensive insurance is essential when choosing the right coverage. Here’s a quick comparison:

  • Third Party Insurance: Covers the damages or injuries to other people and property, but does not cover your own car or injuries.

  • Comprehensive Insurance: Covers both third party damages and injuries to your own vehicle and medical expenses, providing more extensive protection.

The main advantage of third party insurance is its affordability. However, if you are looking for a more complete policy, comprehensive insurance is a better option.

Conclusion: Should You Get Third Party Insurance?

If you’re looking for an affordable way to meet legal requirements or simply want a basic level of coverage, third party insurance is a solid choice. It provides essential protection against damages to other vehicles and people in case of an accident. However, if you want to protect your own vehicle and reduce the risk of financial loss, you may want to consider a comprehensive insurance policy.

At BMI Brokers, we can help you find the best insurance policies that suit your needs. Whether you need third party insurance or comprehensive coverage, our team of experts is here to guide you in the right direction. Contact us today!

For more insights on insurance options, visit our blog for expert tips and guidance!

motorhome insurance

Motorhome Insurance: Essential Coverage for Your Journey in Spain

If you’re planning to explore Spain in your motorhome, securing the right motorhome insurance Spain policy is crucial. Whether you’re a full-time traveler or an occasional adventurer, having comprehensive coverage ensures peace of mind and financial protection against unexpected events.

Why Do You Need Motorhome Insurance?

motorhome insurance

If you’re planning to explore Spain in your motorhome, securing the right motorhome insurance Spain policy is crucial.

A motorhome isn’t just a vehicle; it’s your home on wheels. Accidents, theft, and breakdowns can happen anytime, and the right insurance policy can protect you from costly repairs and liabilities.
Spain has specific legal requirements for motorhome insurance, and without proper coverage, you risk fines, legal issues, or being stranded in a foreign country.

Key Benefits of Motorhome Insurance in Spain

Choosing the right motorhome insurance Spain plan provides numerous advantages:

  • Comprehensive Protection – Covers damages from accidents, theft, fire, and vandalism.
  • Third-Party Liability – Protects you against claims from other drivers or pedestrians.
  • Roadside Assistance – Essential for breakdowns, towing, and emergency repairs.
  • Personal Belongings Coverage – Ensures your valuables inside the motorhome are protected.
  • Emergency Accommodation – Covers temporary lodging if your vehicle is uninhabitable after an accident.

Legal Requirements for Motorhome Insurance in Spain

In Spain, motorhome insurance is mandatory, with at least third-party liability coverage required by law. This ensures that if you’re involved in an accident, any damages caused to other vehicles, property, or individuals are covered. However, many motorhome owners opt for comprehensive policies that offer additional protection against theft, fire, and personal damages.

Types of Coverage: Comprehensive vs. Third-Party

Understanding the difference between insurance policies helps you make an informed decision:

  • Third-Party Insurance: Covers damages to other vehicles and people but does not cover your own motorhome.
  • Third-Party Fire & Theft: Includes third-party coverage plus protection against fire and theft.
  • Comprehensive Insurance: Covers damages to your motorhome, personal belongings, medical expenses, and third-party liabilities.

For peace of mind while traveling in Spain, a comprehensive policy is highly recommended.

How to Choose the Best Motorhome Insurance Spain Policy

  • When selecting a motorhome insurance Spain plan, consider the following factors:
  • Coverage Limits – Ensure the policy provides adequate protection for your motorhome’s value.
  • Breakdown Assistance – Spain has vast rural areas; ensure you’re covered for roadside help.
  • International Coverage – If you plan to travel across Europe, check if your policy extends beyond Spain.
  • Personal Items Coverage – Protects valuables like electronics, kitchenware, and travel essentials.
  • Cost & Deductibles – Compare different providers to find the best balance between affordability and benefit

Tips for Traveling Safely in a Motorhome in Spain

  1. Plan Your Route in Advance – Some roads may not be motorhome-friendly.
  2. Park in Designated Areas – Spain has specific motorhome-friendly sites with essential facilities.
  3. Secure Your Belongings – Theft can occur in tourist hotspots; always lock your doors.
  4. Follow Local Traffic Laws – Speed limits and parking rules differ across regions.
  5. Check Weather Conditions – Avoid driving in extreme heat or heavy rain.

Final Thoughts

Exploring Spain in a motorhome offers an unforgettable experience, but ensuring you have the right motorhome insurance Spain policy is essential. Whether you’re a seasonal traveler or a full-time explorer, comprehensive coverage provides security and peace of mind.

If you’re looking for more expert insurance tips and travel advice, visit our blog!

self-insured retention

Self-Insured Retention (SIR): Everything You Need to Know

When it comes to managing insurance costs, businesses and individuals often explore different coverage structures. One critical concept in liability insurance is self-insured retention (SIR). Understanding how it works, its advantages, and how it differs from deductibles can help policyholders make informed financial decisions.

What is Self-Insured Retention?

Self-insured retention (SIR) is the amount a policyholder must pay out-of-pocket before their insurance coverage kicks in. Unlike a deductible, where the insurer manages claims from the start, with an SIR, the policyholder is responsible for handling and paying claims up to the retention limit before the insurer steps in.

Self-Insured Retention Definition

In simple terms, a self-insured retention (SIR) definition refers to the predetermined financial responsibility a business or individual assumes before their insurance policy starts covering claims.

What Does Self-Insured Retention Mean?

The self-insured retention meaning lies in its role as a risk management tool. It allows businesses to lower premium costs by taking on a portion of the financial responsibility for claims. This structure is common in liability insurance policies, particularly for large corporations and industries with predictable loss patterns.

Self-Insured Retention vs. Deductible: What’s the Difference?

self-insured retention

Understanding Self-Insured Retention helps companies take control of their risk management strategy.

Many people confuse deductible vs. self-insured retention, but they are distinct concepts in insurance policies. Here are the key differences explained:

Who Handles Claims?

  • With a deductible, the insurance company manages claims from the beginning and subtracts the deductible amount from the final payout.
  • With self-insured retention, the policyholder is responsible for managing and covering claims up to the SIR limit before the insurance provider gets involved.

Payment Timing

  • A deductible is subtracted from the insurance company’s payout once a claim is processed.
  • A self-insured retention amount must be fully paid by the policyholder before the insurer begins covering costs.

Impact on Premiums

Choosing a deductible usually reduces insurance premiums slightly.
Opting for self-insured retention can significantly lower premiums since the policyholder takes on more risk.

Common Usage

Deductibles are standard in most personal insurance policies, such as auto or home insurance.
Self-insured retention is typically found in commercial liability insurance for businesses that have the financial capacity to manage claims directly.

How Does Self-Insured Retention Work?

  1. Claim Occurs – A liability claim is made against the policyholder.
  2. Policyholder Pays Up to SIR Limit – The insured covers expenses related to the claim until the retention amount is met.
  3. Insurer Takes Over – Once the SIR threshold is reached, the insurance company begins covering additional costs as per the policy terms.
  4. Claim is Resolved – The insurer handles the remaining financial liability beyond the SIR limit.

For example, if a company has a $100,000 self-insured retention and faces a $500,000 liability claim, they must pay the first $100,000 before their insurer covers the remaining $400,000.

Advantages of Self-Insured Retention

Opting for an SIR structure can provide several benefits:

  • Lower Insurance Premiums – By assuming more financial responsibility, policyholders often pay lower premiums.
  • Greater Control Over Claims Management – Businesses can handle claims directly, giving them more influence over settlements and expenses.
  • Improved Cash Flow Management – Companies can allocate funds for claims strategically rather than paying fixed premiums.
  • Customization of Coverage – Policyholders can tailor their risk management approach to fit their financial situation and industry risks.
  • Potential Savings in the Long Run – If a company has few claims, it may end up saving money compared to paying higher premiums for full insurance coverage.

Disadvantages of Self-Insured Retention

While SIR has advantages, it also has potential drawbacks that policyholders must consider:
High Initial Financial Responsibility – Businesses need sufficient cash reserves to cover high claim amounts before insurance takes effect.

  • Complex Claims Management – Companies must handle their claims until they reach the SIR threshold, which may require additional administrative resources.
  • Potential for Greater Financial Risk – If multiple claims arise in a short period, the financial burden can become overwhelming.
  • Not Ideal for Small Businesses – Small businesses with limited financial resources may struggle to meet SIR obligations.

Is Self-Insured Retention Right for You?

Choosing between self-insured retention vs. deductible depends on various factors, including:

  • Financial Strength – Can you afford to pay large claims upfront?
  • Risk Tolerance – Are you comfortable handling claims before insurance kicks in?
  • Industry Requirements – Some businesses benefit more from SIR due to predictable claims patterns.
  • Insurance Policy Terms – Not all policies offer an SIR option, so reviewing your coverage options is essential.

Companies that have consistent and manageable claim patterns often benefit the most from self-insured retention. If a business has unpredictable or high-value claims, a traditional deductible-based policy may be the better option.

Get the Best Business Insurance with Self-Insured Retention from BMI Brokers

At BMI Brokers, we specialize in Business Insurance solutions that help companies manage risks efficiently, including policies with Self-Insured Retention (SIR) options. Our coverage offers:

Tailored Protection – Customizable policies to suit your business needs.
Cost Control – Reduce premium costs by managing smaller claims internally.
Expert Claims Assistance – Our team supports you every step of the way.
Top Insurance Providers – We work with the best insurers in the market.

Final Thoughts

Understanding what is self-insured retention is key to making informed insurance decisions. Whether you’re a business looking to lower premiums or an individual evaluating risk management strategies, SIR offers a flexible way to balance cost and coverage.

Before selecting an insurance policy with self-insured retention, consider your financial capacity, risk exposure, and claims management ability. Consulting an insurance expert can help determine if this option aligns with your specific needs.

For more insights on insurance strategies and risk management, explore our blog for expert tips and guidance!

health insurance Gibraltar

Health Insurance for Gibraltar: Secure the Best Medical Coverage Today

If you’re planning to live, work, or travel in Gibraltar, having the right health insurance Gibraltar plan is essential. Gibraltar offers a mix of public and private healthcare services, but understanding your options ensures you’re fully protected in case of emergencies.

Why Do You Need Health Insurance Gibraltar?

Health insurance Gibraltar

Stay protected with health insurance Gibraltar, covering emergencies, hospital visits, and routine check-ups.

While Gibraltar has a strong healthcare system, not everyone is automatically covered. Expats, long-term travelers, and digital nomads should consider a comprehensive health insurance Gibraltar plan to avoid unexpected medical expenses.

Key Benefits of Private Health Insurance:

  • Access to Private Clinics & Hospitals – Get faster treatments and specialized care.
  • Emergency Medical Coverage – Protection against high medical costs.
  • Doctor Consultations & Medications – Coverage for routine medical check-ups and prescriptions.
  • Worldwide Coverage Options – Useful if you travel frequently between Gibraltar and other countries.

Public vs. Private Healthcare in Gibraltar

Gibraltar’s public healthcare system, the Gibraltar Health Authority (GHA), provides free medical services to residents and UK nationals. However, non-residents or those without UK ties may need private insurance for full coverage.

Who Needs Private Health Insurance?

  • Expats who are not eligible for GHA services.
  • Remote workers and digital nomads residing in Gibraltar.
  • Tourists and short-term visitors who require temporary coverage.
  • Retirees who want additional medical benefits beyond the public system.

How to Choose the Best Health Insurance Gibraltar Policy

When selecting a health insurance Gibraltar plan, consider the following factors:

  • Coverage Limits – Ensure the policy covers hospital stays, outpatient visits, and specialist treatments.
  • Pre-existing Conditions – Some insurers provide coverage, while others may exclude certain conditions.
  • Emergency Evacuation – Check if your plan covers emergency medical transport to nearby Spain or the UK.
  • Premium Costs – Compare policies to find the best balance between affordability and benefits.

Travel & Health Insurance: A Smart Combination

If you’re visiting Gibraltar, having both travel and health insurance can provide complete protection. For more details, check out: Holidays to Gibraltar: Your Ultimate Travel Guide

Additionally, if you’re traveling frequently or moving abroad, securing a post-departure health policy is crucial. Learn more in: Travel Insurance Already Abroad: Get Covered Even If You’ve Left Home

Is Gibraltar Safe for Medical Care?

Yes! Gibraltar offers excellent medical services, with well-trained professionals and modern healthcare facilities. However, private healthcare may provide faster service and specialized treatments.

If you’re considering a broader travel plan that includes Egypt or Jordan, check out: Best Time to Travel to Egypt and Jordan: A Comprehensive Guide

Final Thoughts

Whether you’re relocating, working remotely, or visiting, having health insurance Gibraltar ensures peace of mind. Understanding your options and choosing the right coverage will protect you against unexpected medical costs while providing access to top-quality care.

For personalized health insurance solutions, contact us today and find the perfect plan for your needs!

Want to learn more about insurance and other coverage options? Visit our blog for expert tips, detailed guides, and the latest insights to help you make the best decisions for your needs!

holidays to gibraltar

Holidays to Gibraltar: Everything You Need to Know Before You Go

Planning holidays to Gibraltar? This British Overseas Territory offers a unique blend of British culture, Mediterranean charm, and stunning landscapes. Whether you’re visiting for history, nature, or a relaxing getaway, this guide will help you plan the perfect trip.

Why Choose Holidays to Gibraltar?

holidays to gibraltar

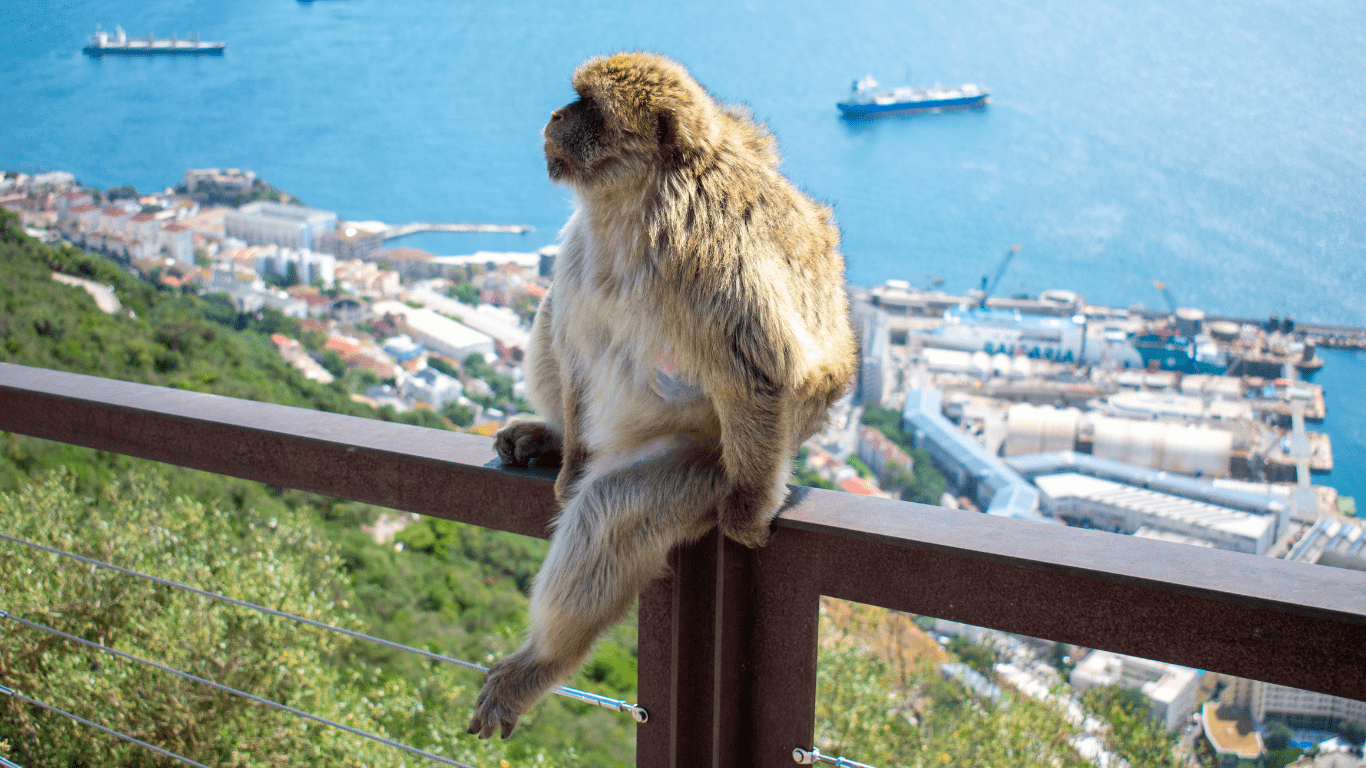
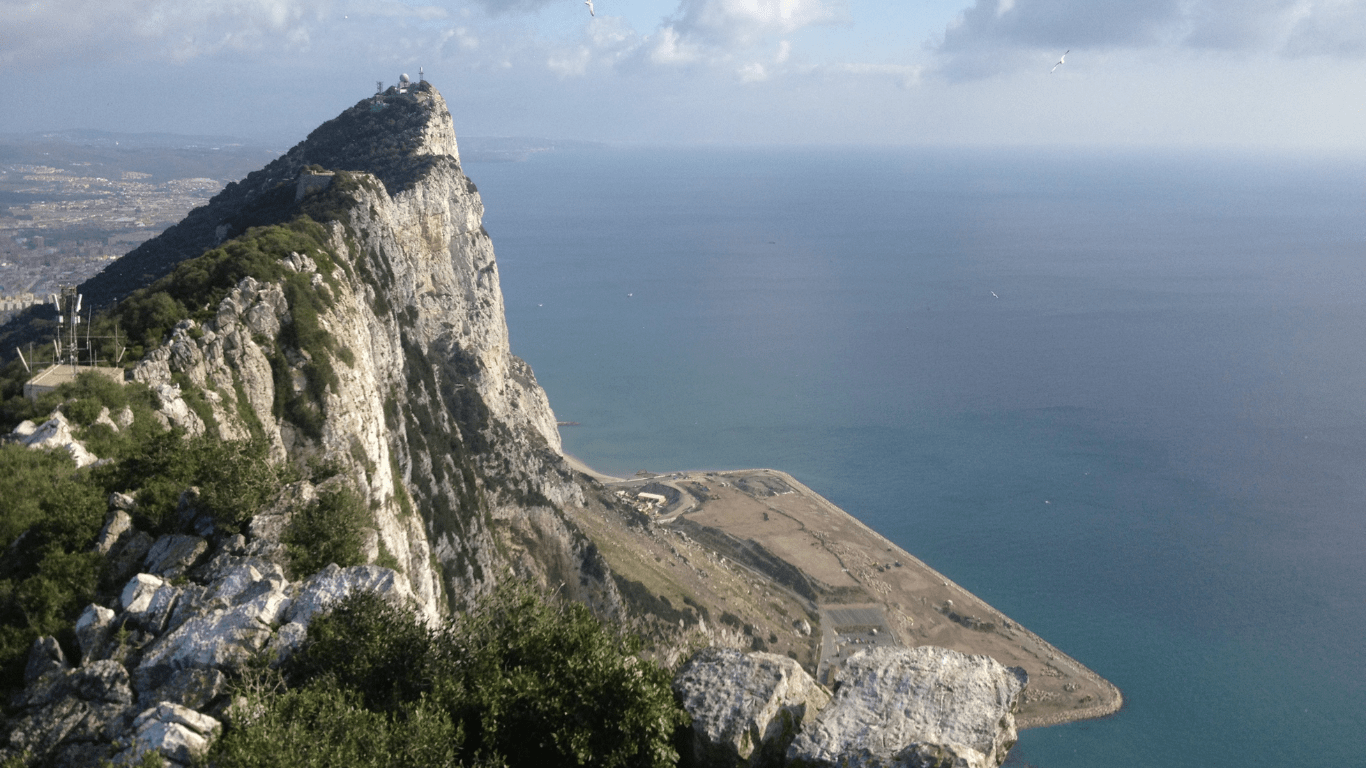
Plan your holidays to Gibraltar and explore iconic landmarks like the Rock of Gibraltar and St. Michael’s Cave.

Holidays to Gibraltar are perfect for travelers looking for a mix of adventure and relaxation. The Rock of Gibraltar, stunning beaches, and rich history make it an attractive destination for all types of travelers.

Top Attractions in Gibraltar

  • The Rock of Gibraltar – Enjoy breathtaking views and meet the famous Barbary macaques.
  • St. Michael’s Cave – A stunning natural wonder featuring dramatic rock formations.
  • Europa Point – A scenic viewpoint where you can see the coast of Africa on a clear day.
  • Gibraltar Botanical Gardens – A peaceful escape with diverse plant life.
  • Main Street – The hub for shopping and British-style pubs.

Getting Holidays to Gibraltar: What You Need to Know

Flying into Gibraltar International Airport is the most convenient way to arrive. The airport is small but efficient, with direct flights from major UK cities and some European destinations.

Alternatively, you can travel via Spain. Many visitors fly into Malaga or Seville and take a scenic drive down to Gibraltar.

Do I Need Travel Insurance for Gibraltar?

holidays to gibraltar

Enjoy unforgettable holidays to Gibraltar with beautiful beaches, vibrant nightlife, and duty-free shopping.

Many travelers ask, “Do I need travel insurance for Gibraltar?” The short answer is yes. Even though Gibraltar has strong healthcare services, medical emergencies and travel disruptions can happen. Having travel insurance ensures you are covered for unexpected medical costs, trip cancellations, and lost luggage.

What Does Travel Insurance Cover?

If you’re wondering, “Do you need travel insurance for Gibraltar?”, here are some key benefits:

  • Emergency medical expenses – Coverage for accidents or sudden illnesses.
  • Trip cancellations – Reimbursement for unexpected travel disruptions.
  • Lost or stolen luggage – Compensation for missing belongings.
  • Personal liability – Protection in case you accidentally cause damage or injury.

For more details on securing travel insurance while already abroad, check out our guide: Travel Insurance Already Abroad: Get Covered Even If You’ve Left Home

How BMI Brokers Supports Your Travel Insurance Needs

At BMI Brokers, we know how important it is to have reliable coverage when traveling. Whether you’re exploring holidays to Gibraltar or venturing further, our comprehensive travel insurance policies ensure you’re protected from unexpected events.

Why Choose BMI Brokers for Travel Insurance?

  • Global Coverage – Our travel insurance plans provide protection no matter where your journey takes you.
  • Emergency Medical Assistance – Get immediate access to medical care, including hospital stays and treatment.
  • 24/7 Support – Our team is available around the clock to assist with medical emergencies, rebooking flights, and handling travel disruptions.

Learn more about our travel insurance options here and enjoy a stress-free trip with complete peace of mind.

Best Time to Visit Gibraltar

The best time for holidays to Gibraltar is between March and October, with warm temperatures and minimal rainfall. However, visiting during spring or autumn ensures fewer crowds and comfortable weather for sightseeing.

For those planning an extended trip, combining your visit to Gibraltar with a tour of Egypt and Jordan can be a fantastic experience. Learn more in our related guide: Best Time to Travel to Egypt and Jordan: A Comprehensive Guide

Final Thoughts

Holidays to Gibraltar offer a fantastic getaway for history lovers, adventure seekers, and anyone looking for a unique travel experience. Whether you’re exploring its historical sites, enjoying breathtaking views, or indulging in British-Mediterranean cuisine, Gibraltar has something for everyone.

To ensure a stress-free trip, don’t forget to secure your travel insurance with BMI Brokers. Contact us now to find the best coverage for your adventure!

Want to learn more about insurance and other coverage options? Visit our blog for expert tips, detailed guides, and the latest insights to help you make the best decisions for your needs!

phone insurance

Phone Insurance: Protect Your Device from Damage, Theft, or Loss

Smartphones have become an essential part of our daily lives, making them one of our most valuable possessions. However, accidents happen—your phone can be dropped, stolen, or damaged by water. Having phone insurance can save you from expensive repairs or the cost of replacing your device. In this article, we’ll explore why insuring an iPhone or any smartphone is a smart decision, the types of coverage available, and how to choose the best mobile phone insurance for your needs.

Why You Need Phone Insurance

Many people believe that a protective case is enough to safeguard their device, but the reality is different. Phone insurance provides financial protection against common risks, including:

  • Accidental Damage: Cracked screens, liquid damage, or other accidental issues can be costly to repair.
  • Theft or Loss: If your device is stolen or lost, cellphone insurance can help cover the replacement cost.
  • Hardware Malfunctions: Some mobile phone insurance policies cover unexpected device failures.
  • Unauthorized Use: If your phone is stolen, some policies offer protection against fraudulent charges.

Without insurance for iPhone or other smartphones, you might end up paying full price for repairs or replacements.

Types of Phone Insurance Coverage

phone insurance

Protect your device with the best phone insurance and stay worry-free.

Not all cellular phone insurance plans are the same. Here are the most common coverage options:

  • Manufacturer’s Warranty vs. Phone Insurance
    A manufacturer’s warranty only covers defects but does not protect against accidental damage or theft. Phone insurance extends coverage beyond what the warranty provides.

  • Carrier-Provided Mobile Phone Insurance
    Many mobile carriers offer cellphone insurance as an add-on, covering loss, theft, and damage. However, deductibles and monthly costs vary.

  • Third-Party Phone Insurance
    Independent insurance providers offer more flexible plans, often with better coverage for accidental damage, loss, and theft.

  • AppleCare+ and Insurance for iPhone
    If you need phone insurance iPhone users trust, AppleCare+ is a popular option. It covers accidental damage and offers reduced-cost repairs.

Protect Your Phone and Other Valuables While Traveling

When traveling, losing money or valuables due to theft can be a stressful experience. While phone insurance ensures your device is covered against damage or loss, it’s also important to consider additional protections. For example, some travel insurance policies may offer compensation if your cash is stolen while abroad. If you’re wondering how this works, check out our full guide on Does Travel Insurance Cover Stolen Cash? Everything You Need to Know. Having the right insurance policies in place can give you peace of mind wherever you go.

How to Choose the Best Mobile Phone Insurance

When selecting a phone insurance plan, consider:

  • Cost vs. Coverage: Compare premiums, deductibles, and what’s covered.
  • Claim Process: A hassle-free claims process is crucial.
  • Replacement Time: Fast device replacement is essential for staying connected.

Conclusion: Insure Your Phone for Peace of Mind

A smartphone is an investment, and protecting it with phone insurance is a smart move. Whether you opt for mobile phone insurance from your carrier, a third-party provider, or AppleCare+ for insuring an iPhone, having coverage ensures you’re protected from unexpected expenses. Don’t wait until it’s too late—insure your phone today!

Looking for more expert insights? Visit our blog for in-depth guides, insurance tips, and industry updates to keep your business protected and compliant!

jet ski insurance

Jet Ski Insurance: Protect Your Water Adventure with the Right Coverage

Owning a jet ski is all about fun and excitement on the water, but ensuring your safety and investment is just as important. Understanding the different coverage options available can help you make an informed decision. In this article, we’ll explore why jet ski insurance is essential, the risks of not having it, and what types of policies you should consider.

Why You Need Jet Ski Insurance

jet ski insurance

Enjoy your ride worry-free with the right jet ski insurance coverage.

Riding a jet ski comes with inherent risks, from accidents to unexpected damages. Having the right insurance coverage can help protect against financial loss in case of:

  • Accidents: Collisions with other watercraft or objects can lead to expensive repairs.
  • Theft: Jet skis are valuable and can be stolen if not properly secured.
  • Liability Claims: If you accidentally cause damage to another person or property, insurance can cover legal and compensation costs.
  • Medical Expenses: Injuries can happen, and some policies may cover medical costs resulting from an accident.
  • Weather Damage: Unexpected storms and rough waters can cause damage to your jet ski, making comprehensive coverage beneficial.

Risks of Not Having Jet Ski Insurance

Without proper jet ski insurance, you could face significant financial burdens, including:

  • Paying out of pocket for damages or repairs.
  • Covering medical expenses if you or someone else is injured.
  • Legal costs if you’re held liable for an accident.
  • Loss of your investment if your jet ski is stolen or damaged beyond repair.

Coverage Options for Your Jet Ski

There are various types of jet ski insurance policies available, each offering different levels of protection. Some of the most common coverage options include:

  • Liability Coverage: Protects you against legal and financial responsibility for damages to other people or property.
  • Collision Coverage: Pays for repairs to your jet ski in case of an accident.
  • Comprehensive Coverage: Covers non-collision-related damages like theft, vandalism, or natural disasters.
  • Medical Payments Coverage: Helps pay medical expenses for you and your passengers.
  • Towing and Assistance Coverage: Covers the cost of towing your jet ski if it breaks down on the water.

Factors That Affect the Cost of Jet Ski Insurance

The cost of jet ski insurance varies based on several factors, including:

  • Make and Model: High-performance and luxury jet skis typically have higher insurance costs.
  • Location: If you live in an area with high rates of theft or accidents, premiums may be higher.
  • Usage Frequency: Using your jet ski more often increases the likelihood of accidents, affecting your insurance rates.
  • Rider Experience: More experienced riders may qualify for lower premiums compared to beginners.
  • Safety Features: Installing security devices and taking safety courses can sometimes reduce costs.

Tips for Choosing the Best Jet Ski Insurance

When selecting jet ski insurance, consider the following tips:

  1. Compare Policies: Research different providers and compare coverage options to find the best fit.
  2. Check Policy Exclusions: Ensure you understand what is and isn’t covered in your plan.
  3. Bundle Your Insurance: Some companies offer discounts when you bundle your jet ski insurance with other policies.
  4. Look for Discounts: Some providers offer lower rates for safe riders or those who complete safety courses.
  5. Read Reviews: Check customer feedback to ensure the provider has a good reputation for claims processing.

Protect Your Entire Watercraft Fleet with Boat Insurance

boat insurance

Having both jet ski insurance and boat insurance ensures complete protection for your watercraft and financial security in case of accidents.

While jet ski insurance is essential for personal watercraft, if you also own a boat, having comprehensive boat insurance is just as crucial. At BMI Brokers, we offer tailored boat insurance policies that protect against accidents, theft, and liability claims, ensuring peace of mind while enjoying the water. Whether you’re cruising on a yacht or towing a jet ski, the right insurance can safeguard your investment.

Conclusion: Stay Informed About Jet Ski Insurance

Owning a jet ski is a thrilling experience, but it’s crucial to understand the potential risks and available insurance options. Be sure to explore different coverage options and choose the right policy to keep your water adventures worry-free.

Looking for more expert insights? Visit our blog for in-depth guides, insurance tips, and industry updates to keep your business protected and compliant!

Louis Vuitton insurance

Louis Vuitton Insurance: Protect Your Luxury Goods with the Right Coverage

Luxury items like Louis Vuitton products aren’t just symbols of status—they are significant investments. Whether it’s an iconic handbag, travel luggage, or other accessories, these items hold considerable value and should be protected. Louis Vuitton insurance, or luxury goods insurance in general, ensures that your investment is covered against damage, loss, or theft. In this article, we’ll explore the importance of insuring your valuable possessions and how we at BMI Brokers can help you find the right coverage.

Why Should You Insure Your Luxury Goods?

Louis Vuitton insurance

Ensure your Louis Vuitton products are covered with the right insurance.

Owning a Louis Vuitton item is a joy, but it also carries the risk of loss or damage. Luxury products can easily cost thousands of dollars or more, making them a substantial investment. This is why insuring your luxury goods isn’t just a smart precaution, but a necessity. Proper insurance ensures that, in the event of damage or loss, you’ll be compensated appropriately.

Without the right coverage, replacing a lost or damaged item can be costly and stressful. Insuring your luxury products provides peace of mind and ensures that your investment remains protected.

The Risks of Not Having Insurance for High-Value Items

Without proper insurance, you expose yourself to several risks, such as:

  • Theft: Luxury items are prime targets for thieves. If a Louis Vuitton item is stolen, insurance could help you replace it or offer compensation.
  • Accidental Damage: Accidents happen, and your luxury goods could be damaged. Whether it’s a spilled drink or a torn material, specialized insurance covers these mishaps.
  • Loss: It’s easy to misplace or lose an item, especially when traveling or using it frequently. Insurance ensures that you are covered in these cases.

Without adequate coverage, you could face significant financial loss if something were to go wrong.

Types of Insurance for Luxury Items

There are various types of insurance that can be tailored to your needs when it comes to protecting high-value items like Louis Vuitton products:

  • Personal Property Insurance: This type of policy covers your luxury items against theft, damage, or loss, whether they are in your home or on the go.
  • Travel Insurance: If you travel often with your luxury goods, travel insurance with coverage for high-value items is a great option.
  • Valuables Insurance: Some policies are specifically designed for high-value items like luxury products, art, or jewelry, ensuring they are adequately protected.

Each type of insurance has its own features, so it’s important to choose the one that best suits your situation.

Conclusion: Secure Your Luxury Investment

A luxury item, like a Louis Vuitton handbag, is more than just an accessory—it’s an investment that should be protected. Having Louis Vuitton insurance for your luxury goods can make a big difference in the event of theft, damage, or loss. Whether through personal property insurance, travel insurance, or valuables insurance, it’s essential to have the right coverage in place.

At BMI Brokers, we’re here to help you insure your luxury products with the best policies available in the market. Protect what matters most and ensure your investment remains safe. Contact us today to learn more about our insurance options.

Don’t risk your luxury products. Contact us today and let us help you find the best insurance policy to protect your valuable items.